Carbon markets
India's carbon market enters its first real cycle: what companies must do now
Verification is done for the first time, the first credits are close, and trading may start in 2027. For about 490 plants, carbon is no longer a report. It is a balance sheet item.
For years, India’s carbon market was something people discussed at conferences. This autumn it became real.
The Carbon Credit Trading Scheme (CCTS), run by the Bureau of Energy Efficiency (BEE), is in its first year of compliance. Covered plants have filed their reports. Independent verifiers have checked them. The first carbon credit certificates are expected soon, and government officials have said that trading on exchanges could start in early 2027 (S&P Global).
In an earlier post I described how India started pricing carbon while Western countries were easing their rules. This post is more practical. It explains how the scheme works, what the first cycle has taught us, and what companies should do now, whether they are covered or not.
How the scheme works, in plain terms
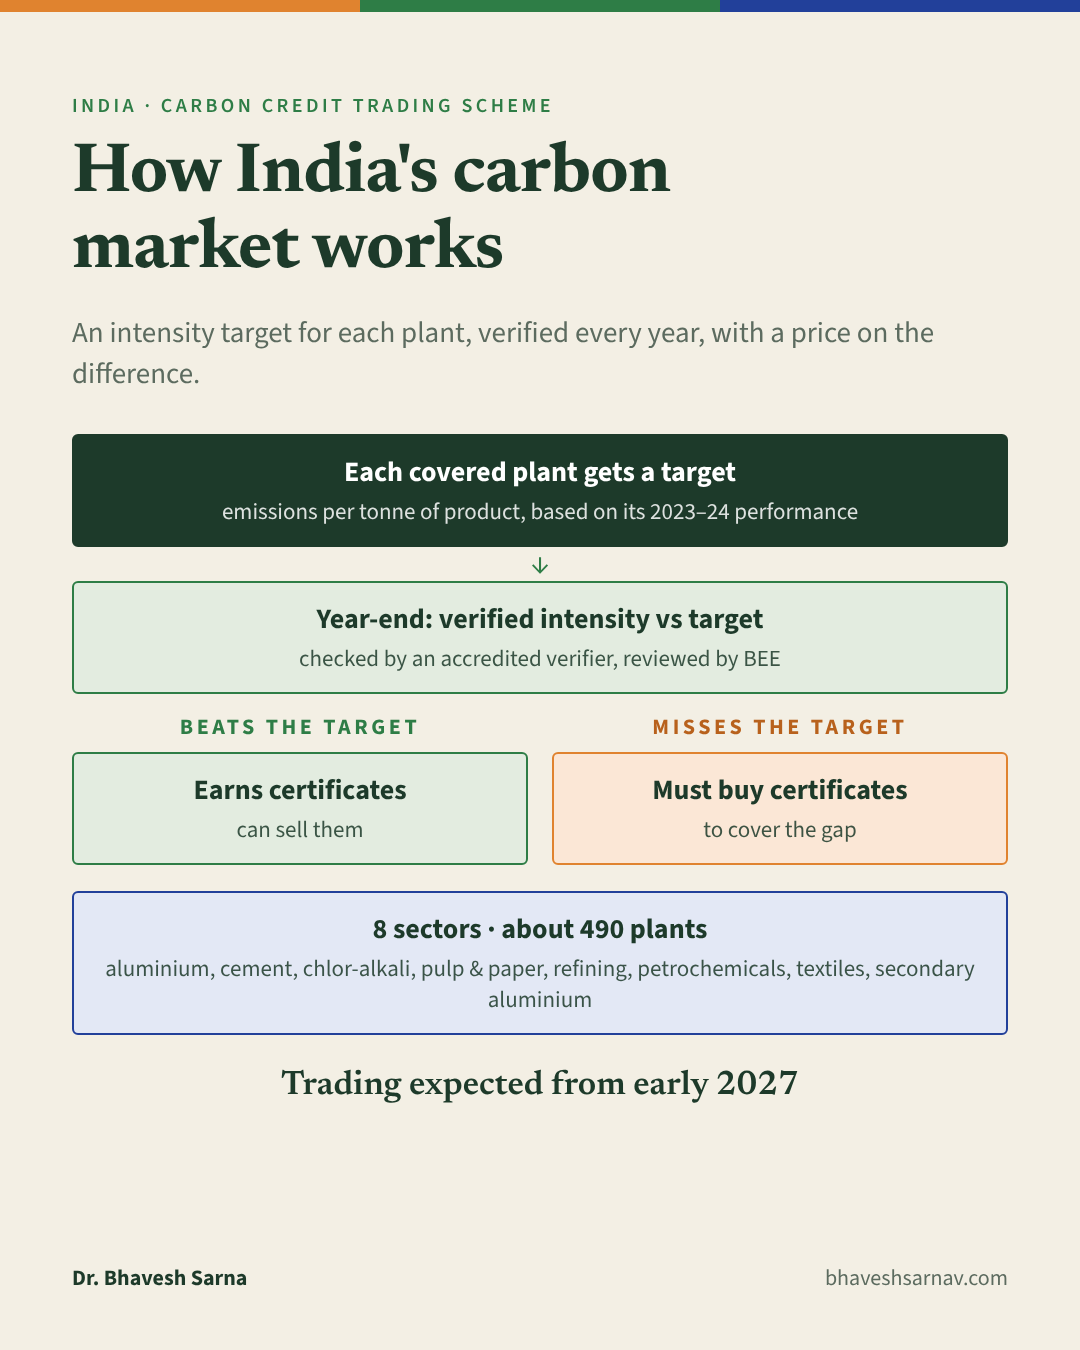
The CCTS does not set a cap on total emissions, as Europe’s system does. Instead, it sets a target for emissions intensity: how many tonnes of greenhouse gas a plant may emit for each tonne of product.
Each covered plant gets its own target, based on its 2023–24 performance. The targets apply to the compliance years 2025–26 and 2026–27.
At the end of the year, the plant’s actual intensity is measured and verified:
- If the plant beats its target, it earns carbon credit certificates for the difference.
- If it misses its target, it must buy certificates to cover the gap.
So a cleaner plant earns money, and a dirtier plant pays. That is the whole idea.
Who is covered
The scheme now covers eight sectors. The first four, announced in October 2025, were aluminium, cement, chlor-alkali, and pulp and paper. In January 2026 the government added four more: petroleum refining, petrochemicals, textiles and secondary aluminium (Outlook Business).
Together that is about 490 plants. According to UNEP’s latest Emissions Gap Report, the scheme initially covers over 700 million tonnes of CO2 equivalent. Steel, one of India’s largest emitters, is expected to follow.
What the first cycle has taught us
The first year of any market is a learning year. Three lessons stand out to me.
1. Data is the real work. Verifiers say this first year needs extra time and “multiple filters of verification”. In a first cycle, the hard part is usually less the emissions than the records: fuel invoices, meter readings, production logs, and the methods to connect them. A plant that has kept clean energy data for years is in a far easier position than one that has not.
2. Verification capacity is still small. BEE published a list of 18 accredited carbon verification agencies only in mid-October. For a market of about 490 plants in eight sectors, that is a thin layer of expertise. Expect delays and some inconsistency in the early years.
3. The market reaches beyond India. The UK has recognised the CCTS as a qualifying carbon price under its own carbon border mechanism, from 1 January 2027. In practice, an Indian exporter that pays a carbon price at home may be able to claim relief at the UK border. This is the first sign that a domestic Indian carbon price can protect exporters abroad. Whether the EU will do the same under its own CBAM is one of the most important open questions for Indian industry.
What covered companies should do now
If your plant is in one of the eight sectors, the first cycle is nearly over. The next one has already started. Here is what I would focus on.
- Treat carbon as a financial item. Your intensity target now has a price attached. Put it in the budget. Know whether you are likely to be a buyer or a seller of certificates, and roughly how many.
- Fix the data before the next audit. Make one person responsible for energy and emissions data. Use the lessons from your first verification to close gaps in metering and records.
- Look at cheap reductions first. Many plants can still reduce intensity through energy efficiency, waste heat recovery, better process control and fuel switching. In a market like this, every tonne you save is a certificate you can sell.
- Link it to your export strategy. If you export to the UK or EU, your verified CCTS data may help you deal with border carbon rules. Keep the two data sets consistent.
What everyone else should do
Even if your company is not covered, the CCTS will reach you.
Suppliers to covered plants will see more questions about the energy and carbon in what they sell. Cement plants will look harder at their fuel suppliers. Textile mills will ask about electricity sources.
Sectors not yet covered, such as steel, chemicals and fertilisers, should prepare now. The government has made clear that coverage will grow. A company that starts measuring today will enter the market with a clear baseline instead of a guess.
Smaller firms can also benefit from the voluntary offset side of the scheme, which allows registered projects to generate credits. This is a separate track, and its rules are still developing, but it may become a source of income for well-designed efficiency and renewable projects.
A market built on trust
A carbon market is only as good as the trust in its numbers. India now has the structure: targets, verification, certificates and soon trading. What it needs next is credibility: consistent verification, transparent prices and firm enforcement.
If the first cycle is handled well, India will have something that very few emerging economies have: a working domestic carbon price that its exporters can point to abroad. That would be a real achievement.
I would like to hear from readers in the covered sectors: what was the hardest part of your first verification, and what would you do differently next year?